In short
- Carriage of own goods is a class of use.
- Carrying tools does not mean they are insured.
- Paid deliveries of other people’s goods need hire and reward.
- Even one business trip needs business cover.
What is carriage of own goods?
Carriage of own goods means using your van for business, including carrying your own tools, materials or stock. It's a class of use that you choose alongside your level of insurance cover.
The name describes how you use the van. It doesn't mean the things inside it are insured. That distinction matters if your working day depends on expensive tools or stock.
Who needs carriage of own goods cover?
If you drive between jobs, visit clients or take tools to a site, you may need this class of use. It's also commonly called business use. Names vary between insurers, so describe what you do rather than relying on the label.
The Motor Insurers' Bureau says even one business trip means you need business cover. Using your van differently from the use stated on your policy can make the insurance invalid.
Commuting is different. Social, domestic, pleasure and commuting use adds travel to a single regular workplace. Social, domestic and pleasure use alone doesn't include commuting.
Our guide to van insurance classes of use explains the distinctions.
What does it allow in everyday use?
Carriage of own goods may cover work journeys and carrying the things you use in your business. The policy wording and certificate set out the uses allowed.
A plumber
Taking your own tools and fittings to customers is business use.
A florist
Explain market trips and deliveries of bouquets you have sold.
A parcel courier
Carrying other people’s parcels for payment needs hire and reward.
A plumber: what should you check?
You drive to customers' homes with your tools, pipework and fittings. This is the sort of work carriage of own goods is intended for. Your tools need a separate check.
A florist: what should you check?
You take your own flowers and display stands to a market stall. Describe this when arranging cover. If you also deliver bouquets you've sold to customers, ask the insurer how those deliveries must be covered.
A parcel courier: what should you check?
You carry other people's parcels for payment. That needs hire and reward cover. Carriage of own goods doesn't cover that work.
When you get a van insurance quote through Vancova, a van insurance specialist will explain the class of use.
Give details of every kind of work journey you make.
How does it differ from hire and reward?
| What you carry | Use to discuss |
|---|---|
| Your own business tools, materials or stock | Carriage of own goods. Describe any customer deliveries. |
| Other people’s goods for payment | Hire and reward, also called courier or haulage cover. |
The key difference is carrying your own business goods or carrying other people's goods for payment. Hire and reward is also sold as courier cover or haulage cover. It applies to work such as paid parcel or food deliveries.
A plumber taking fittings to a job and a courier delivering parcels may drive similar vans along the same roads. Their work still needs different classes of use.
Selling and delivering your own stock is a greyer area. The florist's customer deliveries need checking with the insurer, even though the flowers came from the florist's shop.
Don't assume ownership of the goods settles the question.
If your work includes both trade jobs and paid deliveries, explain both. Check that the certificate allows every use you need.
Read our guide to courier van insurance for more on carrying goods for payment.
Permission to carry your tools does not mean they are insured.
Are your tools and stock insured?
Carriage of own goods lets you carry tools for work. It doesn't itself insure those tools against theft or damage.
Tools in transit cover is usually an add-on or a separate policy. It often has limits for each item and for the total claim. Conditions may apply when you leave tools in the van overnight.
Check what the cover says about your tools' value, storage and overnight parking. A van policy and a tools policy can have different terms.
Our guide to insuring tools in your van explains what to look for.
Goods in transit cover insures the goods you carry. It's usually separate from courier van insurance. Public liability is also separate. Neither is part of a standard van policy, and carriage of own goods doesn't add them.
Which levels of cover can go with it?
Your class of use and level of cover answer different questions. The class describes your journeys. The level describes the protection the van policy provides.
Third party is the legal minimum for driving on UK roads. Your class of use must still match your work.
| Level of cover | What it covers | Your van |
|---|---|---|
| Third party only | Damage or injury to other people, vehicles, animals or property. | Does not pay to repair your own van. |
| Third party, fire and theft | Third party cover, plus fire and theft protection for your van. | Fire and theft cover is subject to the policy terms. |
| Comprehensive | Third party, fire and theft cover, plus cover for damage to your van. | Check the policy terms and exclusions. |
Explore the factors that can affect a van insurance premium.
Can comprehensive cover cost less?
Comprehensive can sometimes cost less than the lower levels. You could ask to see a price for more than one level. Our guide to types of van insurance cover explains each option.
What should you check on the certificate?
Your certificate of motor insurance shows the uses you're covered for. Read it alongside the policy wording. Check that it matches your working day, rather than assuming a business label covers every journey.
- Does the stated use match your trade and the goods you carry?
- Does it allow your journeys between sites and to customers?
- Does it include social use if you also drive the van outside work?
- If you make paid deliveries, does it include hire and reward?
What if your van use changes?
Many business policies include social use, but not all. Ask the insurer about anything unclear. Tell your insurer if your work or use changes.
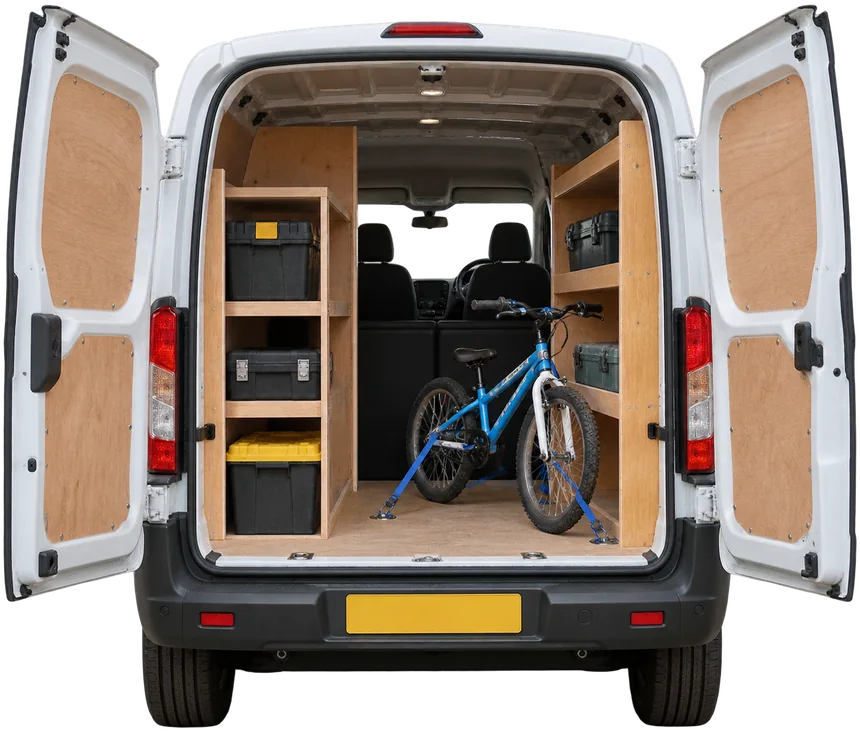
Declare changes from the van's original specification too. These include racking, roof bars and signwriting, even if the change seems minor.
What to have ready for a quote
- Identify your van. Have the registration ready.
- Describe your work. Include your trade, annual mileage and overnight parking.
- List the drivers. Gather licence details and claims and conviction records for everyone who will drive.
- Find your proof. Keep your no claims documents to hand.
Explain what you carry and where you go. For the florist, that means mentioning both market trips and customer deliveries. You can start with the van insurance enquiry form.
A van insurance specialist will get in touch with your quote. The FCA-authorised specialist explains the cover, gives any advice and arranges any policy you choose.
Sending an enquiry does not start cover. Insurance only starts when a policy is in place and its start date and time have been reached.
Common questions
Is carriage of own goods a separate policy?
No. It's a class of use you choose alongside your level of cover. The certificate shows which uses your policy allows.
Can I use it for occasional parcel deliveries?
Carrying other people's parcels for payment needs hire and reward cover. Occasional paid deliveries still need the right class of use.
Does it cover tools left in the van overnight?
The class of use doesn't insure your tools. Check any tools cover for overnight conditions and limits per item and in total.
This guide is general information. Ask the specialist to explain your cover and check the policy terms.
Start your van insurance quote
Start with your reg. A van insurance specialist gets in touch with your quote and explains the cover.
Get a quote